DSLD Mortgage understands the unique challenges self-employed professionals face when refinancing a mortgage.
The Self-Employed Refinancing Challenge
Being your own boss is amazing, but it can make mortgage refinancing more complicated. Lenders have special rules for self-employed borrowers that can make the process feel like an obstacle course.
Who Qualifies as Self-Employed?
- Freelancers
- Contractors
- Small business owners
- Gig economy workers
- Independent professionals
- Self employed homeowners
Lender Requirements for Self-Employed Borrowers
Lenders have specific requirements for self-employed borrowers, which may vary depending on the lender and the type of loan. Here are some common requirements:
- Business License: A valid business license is often required to prove the existence and legitimacy of your business. This document helps lenders verify your self-employed status.
- Tax Returns: Lenders typically require two years’ worth of personal and business tax returns. These documents provide a comprehensive view of your income and help assess your creditworthiness.
- Bank Statements: Providing business bank statements is crucial to demonstrate consistent cash flow and income. Lenders look for healthy financial activity over a period of time.
- Debt-to-Income Ratio (DTI): A DTI ratio of 43% or less is generally required. This ratio helps lenders determine if you can afford the loan payments by comparing your monthly debt obligations to your gross monthly income.
- Credit Score: A good credit score is essential, with most lenders requiring a minimum score of 700. A higher credit score can lead to better interest rates and loan terms.
- Credit Utilization Ratio: Lenders prefer a credit utilization ratio of 30% or less. This ratio indicates how much of your available credit you are using and helps assess your financial responsibility.
- Personal Tax Returns: In addition to business tax returns, personal tax returns are often required to verify your overall income and financial health.
Documentation: Your Refinancing Lifeline
Self-employed borrowers need to prove their income differently than traditional employees. Get ready to gather:
Lenders will also closely examine your credit history, as it is a crucial factor in assessing your creditworthiness. They will look at your payment history and various aspects of your credit report, including any negative remarks, to determine your credit score, which plays a significant role in securing loans and refinancing opportunities.
Crucial Documents
- Tax Returns
- Last 2-3 years of personal and business returns
- Complete documentation
- Includes all schedules and attachments
- Profit and Loss Statements
- Detailed business income records
- Shows your financial stability
- Must be professionally prepared
- Business Bank Statements
- Prove consistent income
- Show healthy cash flow
- Demonstrate financial reliability
- Business License
- Proves your professional status
- Validates your self-employed income
Income Verification Challenges
Lenders look at self-employed income differently:
- Average income over 2-3 years
- Potential income fluctuations
- Business expenses impact income calculation
Self-employed individuals often face unique income verification issues, such as the use of 1099 forms and the eligibility of self-employment income in mortgage applications.
How Lenders Calculate Your Income
- Add business income
- Subtract business expenses
- Use net income for qualification
- Look for consistent earnings
Credit Score Matters More
For self-employed borrowers, credit scores are crucial:
- Higher scores mean better rates
- Shows financial responsibility
- Compensates for income variability
Credit Score Tips
- Keep credit utilization low
- Pay bills on time
- Minimize new credit applications
- Monitor credit report regularly
Debt-to-Income Ratio (DTI)
Lenders carefully examine your:
- Monthly income
- Business expenses
- Personal debts
- Overall financial health
Improving Your DTI
- Pay down existing debts
- Minimize business expenses
- Show consistent income
- Maintain clean financial records
Common Refinancing Hurdles
Challenges Self-Employed Borrowers Face
- Income Inconsistency
- Complex Tax Situations
- More Extensive Documentation
- Stricter Income Verification
Strategies to Improve Refinancing Chances
- Maintain Detailed Records
- Keep immaculate financial documents
- Organize tax returns
- Track business income carefully
- Stabilize Income
- Show consistent earnings
- Minimize income fluctuations
- Demonstrate business stability
- Build Strong Credit
- Pay bills on time
- Reduce outstanding debts
- Maintain low credit utilization
- Separate Personal and Business Finances
- Use separate bank accounts
- Clear financial boundaries
- Easier income verification
Loan Types for Self-Employed Borrowers
Options to Consider
- Conventional loans
- FHA loans
- Bank statement loans
- Stated income loans
Self-employed individuals seeking a mortgage refinance should be aware of the specific requirements and heightened scrutiny they may face from lenders. Understanding what lenders look for in their refinance applications is crucial.
Bank Statement Loan Options
Bank statement loans are a valuable option for self-employed borrowers who may not have traditional income documentation. Here are some common types of bank statement loans:
- 12-Month Bank Statement Loan: This loan option requires 12 months of bank statements to verify your income. It’s ideal for borrowers who have consistent income over the past year.
- 24-Month Bank Statement Loan: For those with a longer track record of stable income, a 24-month bank statement loan requires two years of bank statements. This can provide a more comprehensive view of your financial stability.
- Business Bank Statement Loan: This type of loan uses business bank statements to verify income and cash flow. It’s suitable for borrowers who keep their business finances separate from personal finances.
- Personal Bank Statement Loan: If you use personal bank statements to manage your business income, this loan option can help verify your income and creditworthiness based on your personal financial activity.
Alternative Financing Options
Self-employed borrowers may have alternative financing options available to them, including:
- Non-Qualified Mortgages (Non-QM): These loans do not meet the traditional qualified mortgage requirements but offer more flexible underwriting guidelines. They can be a good option for borrowers with unique financial situations.
- Private Money Loans: Offered by private lenders, these loans often have more flexible terms and can be tailored to meet the specific needs of self-employed borrowers.
- Hard Money Loans: Typically used for short-term financing needs, hard money loans are also provided by private lenders and are secured by real estate. They can be a quick solution for borrowers needing immediate funds.
- Home Equity Lines of Credit (HELOCs): HELOCs allow you to tap into your home equity and use the funds for business or personal expenses. This can be a flexible and cost-effective way to access additional capital.
Red Flags Lenders Watch For
Potential warning signs:
- Significant income drops
- Incomplete documentation
- Inconsistent business records
- Recent business changes
How DSLD Mortgage Can Help
Our Specialized Approach
- Understanding self-employed challenges
- Personalized guidance
- Flexible approach to income verification
- Expert loan officers
Services We Offer
- Free refinancing consultations
- Comprehensive income analysis
- Tailored mortgage solutions
- Guidance through complex documentation
Preparing for Your Refinance
Checklist for Self-Employed Borrowers:
- Gather 2-3 years of tax returns
- Prepare profit and loss statements
- Check and improve credit score
- Organize business documentation
- Review financial health
Overcoming Refinance Application Denial
If your refinance application is denied, don’t lose hope. Here are steps you can take to improve your chances of approval:
- Improve Credit Score: Work on boosting your credit score by paying off existing debt, reducing your credit utilization, and regularly monitoring your credit report for errors.
- Increase Income: Consider ways to increase your income, such as taking on more clients, raising your prices, or expanding your business. Demonstrating higher income can improve your financial profile.
- Reduce Debt: Lower your debt levels by paying off high-interest loans, consolidating debt, and cutting unnecessary expenses. A lower debt burden can improve your debt-to-income ratio.
- Provide Additional Documentation: Strengthen your application by providing additional documentation, such as detailed business financial statements or more recent tax returns. This can help paint a clearer picture of your financial health.
- Consider Alternative Lenders: Explore options with alternative lenders, such as non-qualified mortgage lenders or private money lenders, who may have more flexible underwriting guidelines and be more willing to work with self-employed borrowers.
By following these steps, you can enhance your financial profile and increase your chances of securing a successful refinance.
Final Tips
- Start preparing early
- Be transparent about income
- Maintain clean financial records
- Consider working with a financial advisor
- Don’t get discouraged
Ready to Refinance?
Contact DSLD Mortgage for:
- Free consultation
- Personalized refinancing strategy
- Expert guidance
Disclaimer: Every financial situation is unique. While we provide general guidance, always consult with a financial professional about your specific circumstances.
Contact DSLD Mortgage
- Expert advice
- Understanding your unique situation
- Helping self-employed professionals achieve their home financing goals
Let’s navigate your refinancing journey together!
How much will your mortgage be? You can use DSLD Mortgage’s Mortgage Calculator to estimate your monthly mortgage payment.
Current mortgage rates holding you back? Don’t miss out on these deals! Buy a home with DSLD Mortgage and take advantage of our limited-time mortgage promotions.
Begin Your Home Search with DSLD Homes
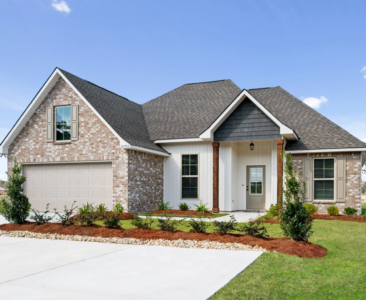
To get a feel for the lifestyle that awaits you in a DSLD Homes community, visit one of their communities throughout the Southern Region.
With a diverse selection of floor plans and communities to choose from, you’re sure to find the perfect fit for your lifestyle.