Quick Answer:
Yes, you can buy or rebuild a home with a mortgage after a hurricane. Before you commit, check the flood zone, repair permits, roof condition, and insurance costs. If you’re rebuilding, confirm local codes and elevation rules first. Your loan options depend on the home’s condition and your personal situation.
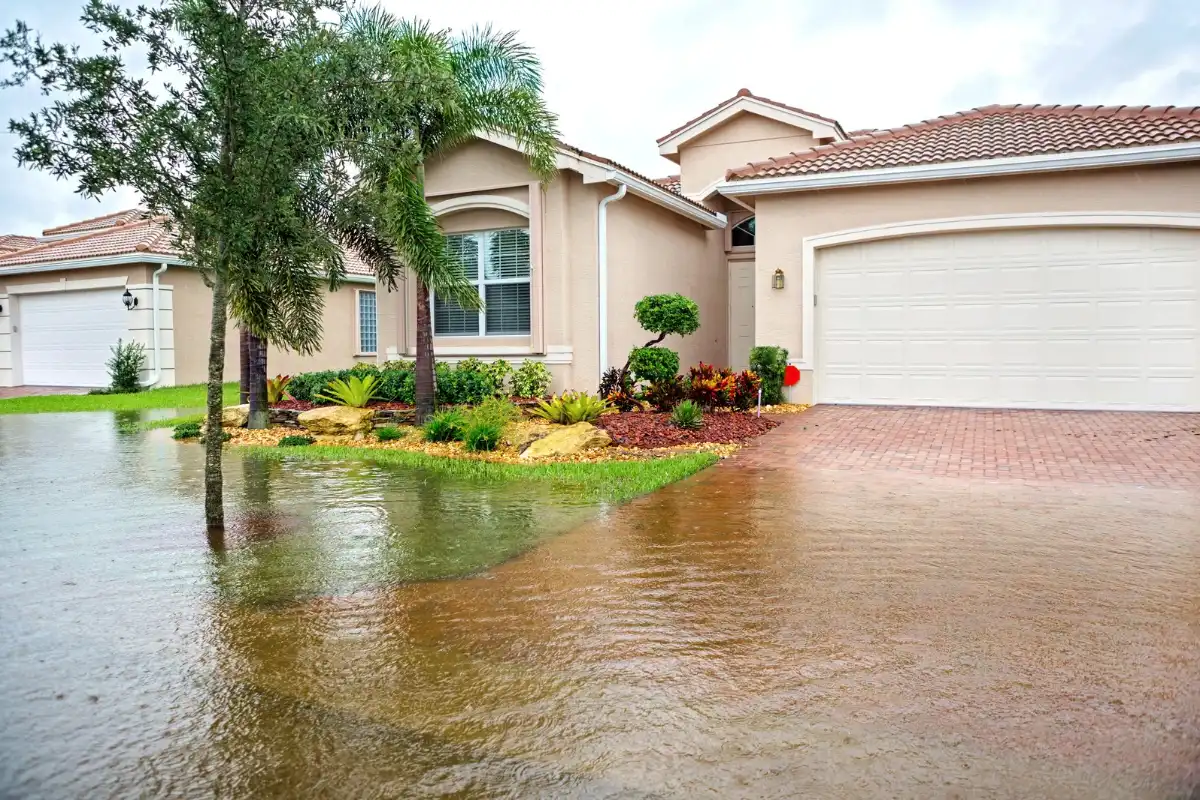
Hurricane recovery brings a neighborhood back to life. New roofs go up, repaired homes hit the market, and owners start planning rebuilds. Still, a home that looks brand new inside may carry old issues. Most sellers made repairs the right way, with permits and strong materials. But there are others who rush the job and the work tends to stay hidden until the next storm or the first insurance quote.
Whether your buying or rebuilding, looking past the fresh paint is a smart move. A careful check before you sign helps you avoid costly surprises. It also keeps your loan on track, since lenders and insurers look closely at homes repaired after a storm.
Can You Get a Mortgage After a Hurricane?
A hurricane doesn’t stop you from getting a mortgage, though the process looks a little different. If you’re buying, the home needs to be safe and livable, or you’ll need a loan that covers repairs. If you’re rebuilding on land you own, a construction or renovation loan may be the better fit.
Keep in mind that FEMA aid and insurance payouts aren’t the same as mortgage financing. FEMA grants help with urgent needs like temporary housing and basic repairs, while insurance pays for covered damage. Requirements also vary by lender, loan type, and the home’s condition, so it helps to talk with a loan officer early.
What Should You Check Before Buying a Home After a Hurricane?
How do you check a home's flood risk?
Start with FEMA’s Flood Map Service Center, where you can look up any address. Zones that start with A or V are high-risk, and lenders require flood insurance there. You’ll need to ask the seller for an elevation certificate, since the home that sits higher usually costs less to insure. From there, you’ll need to find out whether the home flooded during the storm and if the owner filed a claim.
How can you tell if repairs were done right?
Good repairs leave a paper trail. Ask for permits, contractor invoices, and warranties, then confirm with the city or county (or parish) that the permits are closed. Check the roof’s age and whether it meets a wind standard like FORTIFIED, which can lower insurance costs in Louisiana and Alabama. Finally, hire an inspector with storm experience to look for hidden moisture and mold.
What Do You Need Before You Rebuild After a Hurricane?
Rebuilding takes more planning than repairing, since the home has to meet current rules. Before any construction starts, line up these steps:
- Get permits from your city or county/parish and ask which building codes apply now.
- Check the flood zone. In high-risk zones, homes with damage worth half or more of their value usually need elevation or other upgrades to meet current flood standards.
- Get written estimates and timelines from licensed contractors.
- Budget for upgrades like a stronger roof, not just replacing what was there.
If you have NFIP flood insurance, ask about Increased Cost of Compliance coverage. It can pay up to $30,000 toward required upgrades like elevation.
Which Loans Work for a Storm-Repaired or Damaged Home?
The right loan depends on the home’s condition and your personal situation. Below are common options to compare.
Mortgage Options After a Hurricane
Loan Type
Best For
Conventional
Repaired homes in good, livable condition
FHA 203(k)
Buying a home and paying for repairs with one loan
Disaster survivors whose homes were destroyed or badly damaged, with no down payment required
VA
For eligible veterans or service members buying a safe, livable home
USDA
Eligible buyers in qualifying rural areas
Construction loan
Rebuilding on land you already own
A loan officer can help you match the home’s condition to the right option.
How Do Insurance and Hidden Costs Affect Your Budget After a Hurricane?
Insurance is often the biggest surprise for buyers in a recovering area. Your lender collects homeowners and flood insurance as part of your monthly payment. A high premium raises that payment and can shrink your buying power.
Carmen learned this while house hunting in Lake Charles. Her first insurance quote came in at double her estimate, adding $150 to her monthly payment. She asked her loan officer to rerun the numbers. Then she checked with two more insurers and found a better rate, thanks to the home’s newer roof.
Beyond your premium, plan for these costs:
- Hurricane deductibles, which are usually a percentage of your coverage
- Separate wind coverage in some coastal areas
- Elevation, roof upgrades, or other storm protection
- Debris removal or site work if you’re rebuilding
Request insurance quotes before your inspection period ends. Also keep in mind that insurers can pause new policies when a storm is coming, which can delay closing.
Talk to a Loan Officer Before You Make an Offer
Recovering areas can offer solid homes for buyers who come prepared. Before you make an offer, sit down with a DSLD Mortgage loan officer. Together, you can see how insurance and flood coverage fit into your monthly payment. When you’re ready, we’ll help you move forward and find home.
How much will your mortgage be? You can use DSLD Mortgage’s Mortgage Calculator to estimate your monthly mortgage payment.
Current mortgage rates holding you back? Don’t miss out on these deals! Buy a home with DSLD Mortgage and take advantage of our limited-time mortgage promotions.
Mortgage FAQs
Owning a home is a dream we help bring to life every day. You probably have a lot of questions, and that’s a good thing! Here are the answers to some of the most frequently asked questions we get, designed to make your path to homeownership as smooth as possible.
No, flood damage needs a separate policy. NFIP policies usually take 30 days to start, though coverage you buy as part of a home purchase can begin as closing.
Your lender won’t require it, but you may still want it. Floods can reach homes outside mapped zones, and coverage there usually costs less than in high-risk areas.
Call your mortgage servicer right away. You may qualify for temporary payment relief after a declared disaster, but keep making payments until your servicer approves a plan in writing.
Your lender has a stake in the home, so insurers often add its name to the check. The lender may hold the money and release it in stages as repairs get done.
Begin Your Home Search with DSLD Homes
To get a feel for the lifestyle that awaits you in a DSLD Homes community, visit one of their communities throughout the Southern Region.
With a diverse selection of floor plans and communities to choose from, you’re sure to find the perfect fit for your lifestyle.