For many Americans, the dream of homeownership goes beyond purchasing an existing home to building a custom home that perfectly fits their needs and desires. In rural and many suburban areas, the USDA Construction Loan program offers a unique opportunity to make this dream a reality.
I’ve spent years helping people manage USDA Construction Loans, and I’m here to make it easy for you. Let’s break it down and see how these loans can turn that dream home into a reality.
Please Note: DSLD Mortgage does not offer USDA Construction Loans*. Here is a link to find a lender that does*. It is important to choose an approved USDA Construction Loan lender specializing in USDA Construction Loans to ensure a smooth and successful process.
Key Takeaways
- USDA Construction Loans combine the construction and permanent financing into one loan.
- These loans offer 100% financing with no down payment required for eligible buyers.
- The property must be in a USDA-eligible rural area and meet USDA construction standards.
- Borrowers must meet income eligibility requirements and other USDA Loan criteria.
- USDA Construction Loans can be an affordable option for building a home in rural areas.
- USDA Construction Loan requirements include income limits, credit score, debt-to-income ratio, and the need for a USDA-approved contractor.
What Is a USDA Construction Loan?

A USDA Construction Loan is a type of mortgage that combines the financing for both the construction of a new home and its permanent mortgage into a single loan. This program, backed by the United States Department of Agriculture, is designed to promote homeownership in rural and eligible suburban areas by offering affordable financing options. USDA Construction Loans cover various expenses such as buying land, building the home, inspection fees, and permits.
Key Features of USDA Construction Loans
- 100% Financing: Like other USDA Loans, Construction Loans offer up to 100% financing, meaning no down payment is required for eligible borrowers.
- Single-Close Structure: The loan covers both the construction phase and the permanent mortgage, eliminating the need for a separate Construction Loan and then a mortgage.
- Fixed Interest Rates: Interest rates are typically fixed for the life of the loan, providing stability and predictability.
- No Private Mortgage Insurance (PMI): Instead, there’s an upfront guarantee fee and an annual fee, which are typically lower than traditional PMI.
- Extended Loan Terms: Loans can have terms of up to 30 years, helping to keep monthly payments affordable.
- Reduced Closing Costs: USDA Construction Loans can reduce closing costs by consolidating financing applications, which can impact the total loan amount and monthly mortgage payments.
Eligibility Requirements for USDA Construction Loans
To qualify for a USDA Construction Loan, borrowers, and properties must meet several criteria:
- Income Limits: Borrowers must meet the USDA’s income eligibility requirements, which vary by location and household size.
- Credit Score: While there’s no official minimum, most lenders prefer a credit score of 640 or higher.
- Debt-to-Income Ratio: Typically, your debt-to-income ratio should not exceed 41%, although exceptions can be made.
- Property Location: The home must be in a USDA-eligible rural area. Many suburban areas may qualify.
- Occupancy: The home must be your primary residence.
- Property Standards: The construction must meet USDA standards and local building codes.
- Builder Requirements: You must work with a licensed, insured contractor approved by the USDA.
- Satisfactory Credit History: Both the borrower and the contractor must have a satisfactory credit history as part of the USDA’s approval criteria.
The USDA Construction Loan Process
- Pre-Qualification: Determine your eligibility and potential loan amount with pre-qualification.
- Property and Plan Approval: Your chosen lot and house plans must be approved by the USDA.
- Contractor Selection: Choose a USDA-approved builder and get a detailed construction contract.
- Loan Application: Submit your full loan application with all required documentation.
- Underwriting: The lender reviews your application and the construction plans.
- Loan Closing: Once approved, you’ll close on the loan before construction begins. USDA Construction Loans work by combining land purchase and construction costs into a single-close Construction Loan, simplifying the financing process through the Single-Family Housing Guaranteed Loan Program.
- Construction Phase: The lender releases funds in draws as construction progresses.
- Final Inspection: Once construction is complete, a final inspection is conducted.
- Loan Conversion: The Construction Loan automatically converts to a permanent mortgage.
Benefits of USDA Construction Loans
USDA Construction Loans come with a unique set of perks that make them a fantastic choice for building your dream home in a rural area. Here are some of the key benefits:
- Affordable Financing: With 100% financing and competitive rates, it’s an accessible option for many rural homebuyers.
- Simplified Process: The single-close structure streamlines the financing process.
- Custom Home: Build a home that meets your specific needs and preferences.
- Lower Fees: The USDA guarantee fee is typically lower than private mortgage insurance.
- Rural Development: Contributes to the development of rural communities.
- Knowledgeable Lenders: Choosing knowledgeable and transparent USDA Construction Loan lenders is crucial for finding the best rates and ensuring a smooth loan process.
Potential Challenges and Considerations
While USDA Construction Loans offer many advantages, it’s important to be aware of some potential challenges and considerations before you commit:
- Limited Availability: Not all lenders offer USDA Construction Loans.
- Strict Requirements: Both borrowers and properties must meet specific USDA criteria.
- Construction Oversight: The USDA and lender will closely monitor the construction process.
- Time Commitment: Building a home typically takes longer than purchasing an existing one.
- Location Restrictions: The property must be in a USDA-eligible area.
- Comparison with Standard USDA Loan: Unlike a USDA Construction Loan, which combines land purchase and construction into one loan with one monthly payment, a standard USDA Loan is typically used for purchasing an existing home. The USDA Construction Loan offers the benefit of a single closing process, while the standard USDA Loan may be easier to obtain and has fewer construction-related requirements.
Alternatives to USDA Construction Loans
If you don’t qualify for a USDA Construction Loan, consider these alternatives:
- FHA Construction Loans: While they require mortgage insurance, FHA Construction Loans come with low down payments.
- VA Construction Loans: Available to eligible veterans and service members, VA Construction Loans are well worth looking at.
- Conventional Construction Loans: May require a higher down payment but have fewer restrictions.
- Construction-to-Permanent Loans: Similar to USDA Construction Loans but without the rural and income restrictions.
When comparing USDA Construction Loan requirements with FHA and VA Construction Loans, USDA Loans have specific income limits, credit score requirements, and require a USDA-approved contractor, whereas FHA and VA Loans have different eligibility criteria and qualification processes.
Tips for a Successful USDA Construction Loan Experience
- Choose Your Builder Carefully: Work with an experienced, USDA-approved contractor.
- Have Detailed Plans: The more specific your construction plans, the smoother the approval process.
- Budget for Contingencies: Unexpected costs can arise during construction.
- Stay Involved: Regularly communicate with your builder and lender throughout the process.
- Understand the Timeline: Be prepared for the extended timeframe of building a home.
- Understand How USDA Construction Loans Work: Knowing the process of obtaining the loan, its features like simplified financing, and transitioning from a Construction Loan to a permanent mortgage can help ensure a smoother and more successful loan process.
How DSLD Mortgage Can Help
At DSLD Mortgage, we specialize in USDA Loans. Our team of experts can:
- Help you determine if you’re eligible for a USDA Construction Loan.
- Guide you through the complex application and approval process.
- Assist in finding USDA-approved builders in your area.
- Provide support throughout the construction phase.
- Offer alternatives if a USDA Construction Loan isn’t the right fit.
Our expert Loan Officers can help you understand what USDA Construction Loans cover and assist with the application process.
Building Your Rural Dream Home
USDA Construction Loans offer a unique opportunity for eligible borrowers to build their dream home in rural and many suburban areas. With 100% financing, competitive rates, and the ability to combine construction and permanent financing, these loans can make custom homebuilding accessible to many who might otherwise find it out of reach.
However, the USDA Construction Loan process can be complex. It requires careful planning, attention to detail, and a clear understanding of the program’s requirements. That’s where working with experienced professionals becomes invaluable.
If you’re considering building a home in a rural area, don’t let the complexities of construction financing deter you. Reach out to us at DSLD Mortgage, and let our team of experienced professionals guide you through the Construction Loan process. We’re here to help you understand your options, navigate the requirements, and turn your dream of building a custom home into reality.
Remember, your journey to homeownership is unique, and building a home can be one of the most rewarding experiences. With the right guidance and the benefits of a USDA Construction Loan, you can create a home that truly meets your needs and becomes the centerpiece of your rural or suburban lifestyle.
Let’s work together to explore how a USDA Construction Loan can help you build the home you’ve always wanted.
How much will your mortgage be? You can use DSLD Mortgage’s Mortgage Calculator to estimate your monthly mortgage payment.
Current mortgage rates holding you back? Don’t miss out on these deals! Buy a home with DSLD Mortgage and take advantage of our limited-time mortgage promotions.
Your USDA Construction Loan Questions, Answered
Building a new home with a USDA Loan can raise a lot of questions. That’s perfectly normal! To help you feel confident and informed, we’ve compiled answers to some of the most common questions we hear from homebuyers like you.
Funding timelines vary, but typically involve these steps: initial loan approval, construction plan approval, phased fund disbursements (draws), and a final inspection before your loan converts to a permanent mortgage.
These loans are usually for single-family homes or some multi-family properties in USDA-designated rural areas. Agricultural properties and commercial buildings generally don’t qualify.
Unfortunately, no. USDA Construction Loans are specifically for new construction projects. If you’re looking to renovate, you might consider a standard USDA Loan or a different renovation loan product.
It’s smart to plan for unexpected costs! Talk to your lender about potential overages and how they might be handled within your loan. You may need to provide additional funds or adjust your construction plans.
Article Sources
- US Department of Agriculture. “We Are Here for You,” Accessed December 16, 2024
- US Department of Agriculture. “Single Family Housing Guaranteed Loan Program,” Accessed December 16, 2024
- Investopedia. “Guarantee Fees: What They Are, How They Work,” May 22, 2022
- Bankrate. “FHA Construction Loan: What It Is and How to Get One,” October 23, 2024
- Bankrate. “VA Construction Loan: How to Build Your Home via a VA Loan,” June 11, 2024
Find Your Dream Home in a DSLD Community
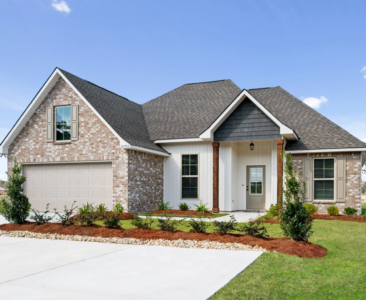
DSLD communities are designed for living. We’re talking spacious floor plans, top-notch amenities, and that warm, welcoming feeling you can only find in a true neighborhood.
Explore DSLD Homes communities across the South and see for yourself. We’ve got something for everyone, whether you’re dreaming of a cozy cul-de-sac or a bustling townhome with all the bells and whistles.